
Best Betting Exchange Sites 2026: Who Actually Holds a UK Licence, and What They Take
 Available in US
The shape of a betting exchange is older than most readers will guess: Flutter and Betfair merged in 2001, with Betfair chosen as the primary exchange, and the flutter site shut its doors in January 2002. Twenty-five years later the model is still unusual enough that the first question most readers ask is the one nobody asks about a normal bookmaker — who exactly is on the other side of this bet? On a betting exchange, a back bet wagers that an outcome will occur and a lay bet wagers that it will not; the layer takes the role a bookmaker normally plays. The exchange itself is not a party to the bets. Because the operator is matching customers rather than quoting against them, it has to be paid another way: most betting exchanges charge commission as a percentage of a customer’s net winnings per market, and losing bets generally incur no commission.
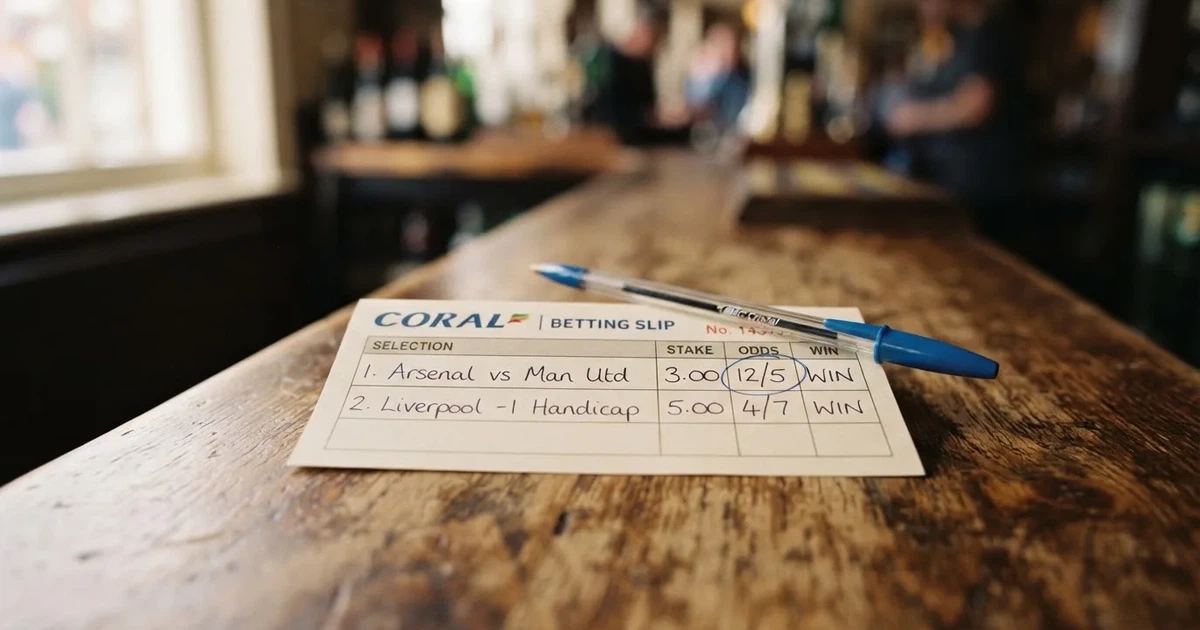
That single fact rearranges the whole page. Where a bookmaker hides its margin inside the price, an exchange charges it on top, so the headline number on the betting slip and the number the operator keeps are separate things. It also rearranges who carries what licence. A bookmaker serving customers in Great Britain needs a Gambling Commission licence wherever it is based; an exchange runs under a different category of that licence — remote betting intermediary — and the Commission’s public register is the whole test of who holds one. The comparison below closes on those licences and those commissions, not on a hand-picked “top” label. A place in a ranked list is not a licence.
Data current as of 30 October 2026; licence claims verified against the Gambling Commission’s public register.
The Statute Behind an Exchange in Great Britain
A betting exchange in Great Britain operates under a specific licence category — remote betting intermediary — issued by the Gambling Commission under the Gambling Act 2005. Since the Gambling (Licensing and Advertising) Act 2014 an operator whose remote facilities are used in Great Britain needs a Commission licence wherever it is based. Sections 33 and 36 of the 2005 Act as amended set that out: a Curaçao, Maltese or Gibraltar licence is not a substitute, and the duty is owed at the point of consumption, meaning the customer sits in England, Scotland or Wales when the bet is placed. Northern Ireland is outside the 2005 Act and has its own older law, so a “GB licence” regulates no Northern Ireland customer even when it covers every other UK postcode.
The Commission’s public register can be searched by business name, trading name, domain or account number and is the whole test of whether a brand holds a licence. The register lists account numbers alongside the trading name and the registered company, so the public check is a mechanical one: type a name, read an account number, and the licence type beside it tells you whether the brand can run a betting exchange, take fixed-odds bets on real events, or only run a more limited format. Brand domains prove nothing: licensed operators use .com as well as .co.uk, and a .co.uk address is no proof that one is licensed either. Every brand reviewed on this page holds a Gambling Commission remote licence; no unlicensed brand is named.
Two licence categories matter most for the comparison that follows. Remote general betting standard (real events) is the standard bookmaker licence — every operator in the ranking holds it except where noted. Remote betting intermediary is the exchange licence; in the featured set, Betfair, Smarkets and Matchbook hold it. A brand that holds only the intermediary licence can match customers against each other but does not have the standard licence to quote prices itself; a brand that holds the standard licence but not the intermediary licence can run a normal sportsbook but not offer back-and-lay markets. Neither is rarer or more prestigious than the other. They are different jobs.
What Playing Safely Looks Like at a GB-Licensed Exchange
Being on the right side of the licensing test pays for itself the day a customer decides to stop. GAMSTOP is the national multi-operator online self-exclusion scheme and a mandatory licence condition for online operators since 31 March 2020; every brand covered on this page is a member. Self-exclusion periods are six months, one year, five years, or five years with auto-renewal, and after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; the separate high-street service covers betting shops in person. A single sign-up covers every licensed brand, which is the only reason a self-exclusion scheme has any teeth.
Identity verification before the first deposit means no anonymous play at a licensed site. Since 7 May 2019, name, address and date of birth are verified before a customer can deposit or gamble — including with a free bet or bonus. The consequence readers actually feel is friction at sign-up: the requirement is the same whether the punter wagers five pounds a week or five hundred. A financial vulnerability check applies to licensed remote betting when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days. It is a public-record check (for example bankruptcy or county court judgments), not an income check and not a credit reference check. Financial risk assessments — the “affordability checks” of the press — were announced in a staged plan published by the Commission on 7 July 2026; no start date has been set, and the published plan is the only statement that can be made about them with confidence. None of this is unique to an exchange. Every operator listed here, exchange or bookmaker, runs under the same identity and affordability rules.
Help lines sit alongside the formal schemes. GamCare runs the National Gambling Helpline, GambleAware funds treatment and education, NHS gambling clinics operate in several regions, and Gamblers Anonymous runs peer-led meetings. Where a brand holds a GB licence, the same customer-protection duties are owed whichever product the punter opens. That, more than any individual welcome offer, is the difference between the licensed set and the offshore alternative named at the foot of this page.
Crypto, Anonymity and Where Neither Appears
A reader who has decided to open a betting exchange account needs to know the regulatory landscape. The honest answer, on the evidence carried into this page, is that the picture is mostly one of caution. The only absolute line is the ban on credit cards for gambling in Great Britain, which has been in force since 14 April 2020 and covers credit-card-funded payments through an e-wallet. Debit cards and bank-based payments are not covered by that ban. Beyond it, what a brand accepts is the brand’s own terms.
That silence is the relevant fact, not a gap to be filled with enthusiasm. A licensed GB exchange runs KYC before the first deposit, which makes an “anonymous” deposit at one a non-sequitur: the exchange has already identified the customer. Pseudonymous on-chain balances and identified exchange accounts are different products in different jurisdictions; conflating them is a common error for those looking for this kind of product. The scoring on anonymity is a function of KYC, payment rails and licence category rather than of any blockchain feature — and on those axes the licensed set here is uniform: every brand identifies the punter, accepts a regulated payment method, and earns no platform anonymity at all.
The practical verdict a reader can act on: a UK punter looking to bet on a GB-licensed exchange does not need a wallet, a coin or a chain to do it. They need a debit card or a bank transfer and a verified identity. Where those are not what the punter wants to use, that is a different product and a different jurisdictional question entirely.
What a Bonus at a Betting Exchange Is and Is Not
The marketing word “bonus” at a sportsbook covers several different products, and at a betting exchange it covers fewer of them than at a bookmaker. The licences held by the three exchange-category operators in this ranking — Betfair, Smarkets and Matchbook — grant a wider set of products than a pure intermediary licence, and the welcome offer attached to each is set out in the operator’s own terms. Reading those terms carefully is the test, not the headline number. A cash bonus stays a cash bonus; a free bet stays a free bet, whose stake is usually NOT paid back with a win; a “risk-free” bet refunded as a free bet is not a refund in money; a price boost, an accumulator insurance and a cashback each stay what they are. The promotional rules in force since 19 January 2026 cap wagering requirements on bonuses at 10x (so a £10 bonus at the old 50x needed £500 of bets; under the cap no more than £100), and mixed-product promotions — an offer that requires gambling on two or more product types such as betting, casino, bingo and lottery, for example “bet on football to get free spins” — are banned.
Two consequences follow. First, exchange-style “0% commission for 60 days” promotions — such as the new-customer offer Smarkets has run, which pairs the zero-commission period with a minimum first deposit of £10 — read cleanly against the licence. They are adjusting the one charge the exchange model imposes, which is a direct benefit to the punter rather than a wrapper around the same underlying price. Second, the exchange welcome offer looks structurally smaller than a sportsbook’s because it is a different instrument. A £50 free bet on a sportsbook is a refund of a losing stake as a bet credit; a “0% commission for 60 days” at an exchange is a discount on the price of every winning bet for two months. Two products, two economics, two reasons the headline figure does not compare.
Whether the wagering cap applies to free bets with no wagering condition, and any cap on the money value of a bonus, are not established; the rule as written applies to offers where a wagering requirement exists. The reader-facing move is the same one that holds across this page: read the terms before claiming, and judge the offer on its actual mechanics, not its headline.
What the App and the Browser Are Actually Doing
A betting exchange’s app is its main front door; desktop usage is concentrated in serious traders and a long tail of casual punters who arrived on a different platform first. The actual capability across the licensed set is narrower than a sportsbook’s, because the product itself is narrower. Back and lay are present on every licensed exchange app in this ranking; in-play markets exist where the platform supports them (Betfair, Matchbook and the sportsbook side of Midnite list in-play; the rest of the pure-intermediary set is more limited). Live streaming of in-house events varies by product: Betfair lists free live streaming of events such as UK and Irish horse racing and football inside its app, and Matchbook lists live streaming of horse racing and greyhounds. None of that is the whole feature set; every brand has its own catalogue and exclusions in its own terms.
What does not change is the read-between-the-lines property of an exchange app: because the screen is presenting bids and offers rather than a bookmaker’s single line, latency and price-update freshness are the measures that matter, not how many markets are listed. An exchange whose prices lag the in-play clock is broken regardless of how many sports it offers. The App Store ratings carry a hint — Midnite lists a sports welcome offer and acca-builder features alongside the in-play events, the kind of surface breadth an exchange cannot match — but a serious reader will trade opening a small position with a sportsbook’s app first to feel the difference before committing a bankroll to a particular platform.
Browser use is supported everywhere and recommended for the layout of multiple markets. Mobile is the medium most customers use, and any platform that has shipped a sub-standard app has heard about it in reviews faster than any bookmaker would. The consequence is the same as on the desktop: less UI to learn, more markets to dig through, and a price ladder that updates within seconds.
In-Play, Cash Out and the Difference Between “Trading” and “Betting”
A punter on a betting exchange can do in-play the same things a bookmaker punter can do, plus a few the bookmaker cannot offer. The first is the lay bet: a punter can take a price against an outcome happening at the same odds they would otherwise have backed it for, locking in a position before the event resolves. That is the trade that turns betting into something closer to financial trading, and it is what gives an exchange its identity. In-play trading — taking a small profit by laying a bet off at a shorter price than was backed, or cutting a loss at a longer one — is the activity the licence category is built around.
Cash out at an exchange is a separate mechanism with a different cost. Where a sportsbook’s cash out is a function of the bookmaker’s own price, an exchange’s cash out is the user placing the offsetting lay bet themselves (or letting the platform place it for them as a “cash out” button). The price is whatever the next available layer is offering; the spread is the difference between the best back price and the best lay price on that outcome at that moment. Cash out availability is not guaranteed, and at one sportsbook in this comparison the listed help page states that cash out may be unavailable and that bets stand if it is unavailable — a sentence which is as relevant at an exchange as it is at a sportsbook.
The consequence for the punter is a wider menu of approaches and a wider menu of errors. In-play on an exchange rewards speed and pre-event preparation. A punter who arrives mid-match without a thesis is a punter the market is taking a position against. None of the operator brands reviewed here promises the punter a winning position; the platform exposes prices and charges on results.
Strategies and Systems: What “Betting Exchange Laying System” Actually Means
A common strategy core is the ‘laying system’, which sits beside the basic back-and-lay mechanic. A laying system is a sequence of bets at an exchange in which every wager is a lay — a bet against an outcome happening — and the bettor’s edge is supposed to come from the price they accept rather than from any predictive edge in the event. Common lay systems include pre-event lays on short-priced favourites, in-play lays after a goal or wicket, and “stop at a loss” trajectories where the bettor commits to a maximum liability per cycle. None of them beat the market over a small sample, because the market is the entity on the other side; the reader should assume that any system advertised as “winning” is selling a difference of opinion and not a structural edge. What a lay system does is impose discipline, which is the genuine product on offer.
Two implications follow. The first is liability: liability is the most a person can lose in the worst case. A lay bet whose lay stake is £10 at odds of 6.0 means a liability of £50 — the stake multiplied by (odds − 1). A punter betting in singles rather than accumulators gives themselves a known maximum loss per cycle, which is what the system trades off against wins. The second implication is the position on the betting slip: a lay of Arsenal at home for £10 at 1.50 is the same shape as a back of a draw at a different bookmaker for the same event. Different instruments; same £10 input if the punter is matching stakes, different £50 worst-case liability.
A bankroll and a position-sizing rule are what serious users actually carry. Forecasts and analytics are useful inputs; they are not systems by themselves. The reader who treats the system as the discipline rather than as a sequence of selections is the reader who treats the exchange as the product it actually is — a marketplace rather than a tip sheet.
Bet Types, Accumulators and What an Exchange Will and Won’t Take
Betting exchanges will not offer every product a sportsbook does. A real-money betting exchange limits its markets to the ones customers will actually back and lay against each other in size. That typically includes the most popular horse racing and football markets, in-play trading on major sports, and a long tail of smaller sports where liquidity is thinner. Betting exchanges generally limit odds to between 1.01 and 1000, and bet sizes are not restricted as long as opposing customers match the stake. There is no bottom of the market an exchange will refuse to clear; there is a top of the market where almost no customer will back it.
Accumulators at an exchange are structurally different from accumulators at a sportsbook. At a sportsbook, an accumulator is a single bet whose odds are the product of the legs’ odds. At an exchange, every leg is an independent back or lay against other customers, so an “accumulator” is a sequence of independent bets whose results are visible separately as the event unfolds. A punter can trade out of any leg in-play at the next available price; a sportsbook punter cannot. Betfair Sportsbook lists a Bet Builder offering alongside its other products, and Matchbook lists Bet Builder and multiples, so the sportsbook side of the licensed exchange operators competes on the same product surface as a normal bookmaker. The exchange side of those brands is the more limited offering.
Settling markets on an exchange happens market by market. A non-runner in a horse race is removed from the market and the position is cancelled at the exchange (with the punter’s stake returned in full); the equivalent at a sportsbook may be settled under a Rule 4 deduction. Each-way at an exchange is a back-to-win and a back-to-place, two separate bets with two separate stakes; at a sportsbook, an each-way bet is two bets of equal stake (so the total stake doubles), with place terms that vary by race. Liquidity is the constraint an exchange cannot finesse: a market with one backer and one layer settles regardless of how thin the book is. A market with no backers and no layers does not exist at all.
A table sits below summarising how the licensed brands line up against each other. Where a column cannot be filled for most rows, it is dropped entirely — a column of em dashes is not information. The four columns here are the four that hold information across every brand in the set.
| Brand | Gambling Commission remote licence (account number) | What the operator’s own terms say on the exchange subject |
|---|---|---|
| Betfair | 39439 — PPB Counterparty Services Limited — categories on the register include remote betting intermediary | Back and lay across sports; in-play markets; Betfair Sportsbook lists in-play betting, Bet Builder and free live streaming of events such as UK and Irish horse racing and football within the app, plus a 90 Minute Payout market |
| Smarkets | 39173 — Smarkets (Malta) Limited — remote betting intermediary | Standard commission of 2% on eligible exchange bets; new customers have been offered 0% commission for 60 days with a minimum first deposit of £10 |
| Matchbook | 39504 — Triplebet Limited — categories on the register include remote betting intermediary and remote general betting standard (real events) | Customers bet against other users, with Bet Builder, multiples, in-play betting and live streaming of horse racing and greyhounds |
| Kalooki Sportsbook | 57730 — Kalooki Sportsbook Limited — remote general betting standard (real events) | A sportsbook product; exchange-style back-and-lay markets are not the listed core offering |
| BetTom | 64959 — Bet Tom Limited — remote general betting standard (real events) | A sportsbook product rather than an exchange; welcome offer: 50% back as a free bet of up to £50, with a matching 50% back up to £50 as free slot funds, full terms apply |
| DAZN Bet | 48756 — DZBT Limited — remote general betting standard (real events) | A sportsbook product; lists Cash Out, Bet Builder, daily bet boosts and in-play betting; cash out availability is not guaranteed and bets stand if unavailable |
| Midnite | 101839 — Midnite Limited — remote general betting standard (real events) | A sportsbook with in-play events, an acca builder, popular accas and price boosts with maximum-stake limits; sports welcome offer: £5 or more on pre-match odds of EVS (2.0) or greater within 14 days of sign-up yields £25 in free bets and 50 free spins, valid for 7 days |
| Star Sports | 9177 — Star Racing Limited — remote general betting standard (real events) | Pre-event and in-play markets with Bet Boosts, Daily Specials, Weekend Enhanced Boosts and in-play betting on football, horse racing, golf and US sports |
| Fafabet | 57385 — Taichi Tech Limited — remote general betting standard (real events) | Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: if the starting price is bigger than the original price, the bigger odds are paid |
| Bet600 | 44731 — Tyche Tech Limited — remote general betting standard (real events) | Best Odds Guaranteed on horse racing: if the starting price is bigger than the early or show price taken, the bet is paid at the SP |
The table makes the structural feature plain. Three of the ten licensed brands above — Betfair, Smarkets and Matchbook — hold remote betting intermediary on their licence, which is the licence category for running an exchange. The remaining seven are sportsbook operators licensed for fixed-odds betting on real events. Several licensed brands can run under one licensee, and the table does not collapse them into one entity. Paddy Power and Betfair, for instance, are operated by PPB Counterparty Services Limited, which is a single licensee running two products.
The Ten Licensed Brands, Reviewed One by One
Betfair — The Most-Developed Exchange in the Set
Betfair’s licence category on the register includes remote betting intermediary, and it is the operator whose exchange product the comparison centres on. The licensing arrangement sits with PPB Counterparty Services Limited under account 39439, which means Betfair and Paddy Power are operated by the same licensee; they are not independent operators. The sportsbook side offers in-play betting, a Bet Builder, and free live streaming of events such as UK and Irish horse racing and football within the app, plus a 90 Minute Payout market. Best odds guaranteed and the broader sportsbook product sit on the sportsbook side of the same licence. The exchange product is the strongest on this list: liquidity on the major football and horse racing markets is the deepest among licensed GB exchanges, and that depth is what makes an exchange a marketplace rather than a sign-up page. Betfair’s verdict is the most-developed choice for the punter who actually wants an exchange rather than a sportsbook that talks about one.
Smarkets — Lower Commission, Thinner Catalogue
Smarkets applies a standard commission of 2% on eligible exchange bets, and its new-customer offer has paired a 0% commission period for 60 days with a minimum first deposit of £10. The licensee is Smarkets (Malta) Limited under account 39173, and the licence category on the register is remote betting intermediary. Smarkets is a cleaner instrument than the deeper-market alternatives because the commission is lower and the platform makes the commission case at the front of the sign-up rather than burying it. The other side of the same coin is liquidity: at the time of the most recent set of conditions reviewed, Smarkets carries fewer markets and shallower books than Betfair on the major football and horse racing events. The verdict: best on price among GB-licensed exchanges, weaker than Betfair on catalogue depth.
Matchbook — An Exchange With a Real Sportsbook Layer
Matchbook’s licence lists both remote general betting standard (real events) and remote betting intermediary, which makes it a hybrid: an exchange and a sportsbook on one licence. The licensee is Triplebet Limited under account 39504, and the platform’s product page describes customers betting against other users with Bet Builder, multiples, in-play betting and live streaming of horse racing and greyhounds. The combination is rarer than the alternative: a sportsbook front end that lets the punter back a price and a betting exchange underneath where liquidity sits. Matchbook’s verdict is the strongest answer for the reader who wants both products under one brand without two separate accounts.
Kalooki Sportsbook — Smaller Sportsbook on the Register
Kalooki Sportsbook is operated by Kalooki Sports Book Ltd (company number 12938274), licensed by the Gambling Commission under account number 57730, and is a GAMSTOP member. The verdict is the small-register sportsbook: a brand on the public register, named and address-checked, GAMSTOP-enrolled and KYC-compliant, with a thinner marketing footprint than the bigger names in the set. A reader who values the licence over the catalogue gets a clean answer here; a reader who wants the deepest product gets it elsewhere.
BetTom — Sportsbook With a Two-Tranche Welcome
BetTom’s sports welcome offer is 50% back as a free bet of up to £50, paired with a matching 50% back up to £50 as free slot funds for casino play; full terms apply. The licensee is Bet Tom Limited under account 64959. The structure is a familiar bookmaker construction — a sports offer and a casino offer, separated only by the customer’s first product choice — and the reader’s working assumption is that the two halves share terms around minimum odds, expiry, and free-bet settlement. BetTom’s verdict is the welcome-offer reader who reads the terms before claiming. The free bet stake is generally not paid back with a win, which is the standard trade-off across this product class and not specific to this brand.
DAZN Bet — Sportsbook With Cash Out as the Headline
DAZN Bet offers Cash Out, Bet Builder, daily bet boosts and in-play betting; cash out availability is not guaranteed and bets stand if it is unavailable. The licensee is DZBT Limited under account 48756. The cash-out headline is honest about its own limits: every operator’s help page says the same thing about unavailability, but this one states it openly. The verdict is the sportsbook reader who trades positions in-play and reads the small print.
Midnite — Sportsbook With a Card-Based Welcome
Midnite’s site cites Gambling Commission account 101839 and shows in-play events, an acca builder, popular accas and price boosts with maximum-stake limits. The licensee is Midnite Limited. The sports welcome offer is £5 or more on pre-match odds of EVS (2.0) or greater within 14 days of sign-up, which yields £25 in free bets and 50 free spins, valid for 7 days. The 14-day window from sign-up and the 7-day window on the free bets are the two clocks to remember. Midnite’s verdict is the welcome-offer reader who can place the qualifying bet inside two weeks and use the bonus inside one more week.
Star Sports — Sportsbook With Daily Specials
Star Sports offers pre-event and in-play markets with Bet Boosts, Daily Specials and Weekend Enhanced Boosts, plus in-play betting on football, horse racing, golf and US sports. The licensee is Star Racing Limited under account 9177 and the licence category is remote general betting standard (real events). The product is a familiar shape: price boosts above the standard line, special events at the front of the page, in-play across several sports. The verdict is the prices-and-specials reader; whether the specials beat the standard line is something the reader checks on the day.
Fafabet — Sportsbook With Best Odds Guaranteed
Fafabet pays Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: if the starting price is bigger than the original price, the bigger odds are paid. The licensee is Taichi Tech Limited under account 57385 and the licence category is remote general betting standard (real events). Best Odds Guaranteed is one of the more durable promotions on the GB sportsbook market, paid on the standard product. Fafabet’s verdict is the racing reader who knows what BOG pays and what it does not.
Bet600 — Sportsbook With Best Odds Guaranteed on a Narrower Product
Bet600 pays Best Odds Guaranteed on horse racing: if the starting price is bigger than the early or show price taken, the bet is paid at the SP. The licensee is Tyche Tech Limited under account 44731 and the licence category is remote general betting standard (real events). The BOG mechanism is the same shape as Fafabet’s; the product surface around it is thinner. The verdict is the racing reader who values the BOG promise over the catalogue.
Pricing, Margin and the Sample Two-Way Market
The book’s edge on a fixed-odds sportsbook lives inside the price. The exchange’s edge lives in the commission. That structural difference is what the published odds look like, and the simplest way to see it is to work the margin on a sample market and compare it against the headline commission at the same exchange. The arithmetic is illustrative, not a quoted price.
Consider a two-way market at decimal odds of 1.90 against 1.90. The payout share across both outcomes is calculated as 1 ÷ (1 ÷ 1.90 + 1 ÷ 1.90). The two equal prices imply an inverse of approximately 1.0526 each, summing to about 2.1053; one divided by that sum yields a payout share of about 0.475, or 47.5% per unit bet on this market. The margin is 1 − payout share, which comes out to about 52.5% on this book. That is a deliberately wide book — an honest two-way example priced at 1.90 each, the kind an exchange would not post and a sportsbook would never write. The point of the example is that the bookmaker’s edge is the gap between 100% and the payout share, and an exchange posting the same two prices would leave a margin that no punter would back.
Apply the same arithmetic to a tight market. The same 1.90/1.90 example gives a margin that only the lay side of an exchange could face for long; a real exchange market price on a competitive football match comes closer to 1.98/1.98 — close to even money on either side — and a back of one outcome at that price prices the layer in at roughly 1.98 too, leaving a margin in the low single digits, the kind of margin that a sportsbook almost never quotes. The bookmaker’s edge is the gap between 100% and the payout share, and the exchange’s edge is the 2% commission on the punter’s net winnings. The two costs are paid at different points in the bet’s life and on different sides of the same transaction.
Reported as a band rather than a single number: a sample two-way market at 1.90/1.90 yields a margin around 52% per unit staked — the deliberately wide book example above; a sample two-way market at the even-money end of an exchange’s actual offering yields a margin closer to the 1-2% range, the structural feature that puts exchanges above fixed-odds sportsbooks on price for any punter able to back the right side of the trade. The condition that makes the band land where it does is the depth of the book on each outcome — every additional layer at the same price reduces the margin by the same fraction of the implied probability — and the absence of a margin-weighting the sportsbook always carries in its prices.
How a Punter Uses This Page
A reader who has decided to open a betting exchange account can read this ranking as a sequence of three questions. First: is the platform licensed for the activity the reader actually wants to do? A brand whose licence is remote general betting standard (real events) without the intermediary category is not running an exchange, regardless of how the front page is worded. Second: what is the commission rate on the punter’s market at the stakes the punter intends to use? Smarkets’ 2% is the published rate on eligible exchange bets and the new-customer 0% period is a discount on it; Betfair and Matchbook publish their own structures and the reader checks them on the day. Third: what does the platform publish about how it handles disputes, withdrawals, and self-exclusion? The Commission register gives the licence; the brand’s own terms and the identity check at sign-up give the rest.
A reader who has decided not to open an exchange account can read the same ten brands as a comparison of GB-licensed sportsbooks, with three of them carrying a different product alongside. That is the read the table makes possible, and it is the reason a comparison of “best betting exchange sites” is wider than three names.
Crypto, Crypto-Branded and Other Operators Outside the GB Licence
A reader who has seen a brand or a wallet advertised in the same market segment should treat any such brand as outside the GB-licensed set covered above. The principle is settled: a Curaçao, Maltese or Gibraltar licence is not a substitute, and the duty is owed at the point of consumption. A punter who uses an unlicensed brand gives up the named protections listed in the licence section above and should not assume any redress if funds are withheld; the only accurate framing is that licensed = checks, limits, GAMSTOP, bonus cap, and verification before the first bet, while unlicensed = none of those protections and possible loss of funds. The descriptions of any platform outside this set would be made on the operator’s own terms and not on the public register.
Frequently Asked Questions
How does a betting exchange work?
A betting exchange is a marketplace where customers bet against each other on the outcome of discrete events, and the exchange itself is not a party to the bets. A back bet wagers that an outcome will occur and a lay bet wagers that it will not; the layer takes the role a bookmaker normally plays. Most exchanges charge commission as a percentage of net winnings per market, and losing bets generally incur no commission, which is why exchange odds are usually better because overrounds are smaller. Liability is the most a punter can lose on a lay bet, calculated as stake × (odds − 1).
How can it be checked that a bookmaker holds a Gambling Commission licence?
The Commission’s public register is the whole test of who holds a licence and can be searched by business name, trading name, domain or account number. Type the brand name, read the account number beside it, and confirm the licence type matches the product the reader wants. Every brand in the comparison above holds a remote licence of the kind the register lists; a brand not on the register is not licensed for the activity, and a .co.uk address proves nothing. Where the licence is held by a parent company, the register shows the parent and the trading name together, which is the canonical test of who runs the brand.
How is the return on a bet worked out from the stake and the odds?
For a single bet, return = stake × odds, and net profit = stake × (odds − 1). For a combination bet, the odds of the legs multiply into one price, and the same two formulas apply to the combined stake. An each-way bet is two bets of equal stake (so the stake doubles), with place terms that vary by race and by operator; the formula above applies to each half separately. The promotion called Best Odds Guaranteed pays at the bigger of the original price and the starting price, so the formula is applied twice and the higher result is paid. None of the formulas involve any margin built in — the operator’s edge is hidden in the price.
What is the bookmaker’s margin and how can it be seen in the odds?
The margin of a market is 1 minus its payout share; for a two-way market with decimal odds o₁ and o₂, the payout share is 1 ÷ (1 ÷ o₁ + 1 ÷ o₂), so the margin is 1 − 1 ÷ (1 ÷ o₁ + 1 ÷ o₂). Where two prices sum to about 2.0 across the outcomes, the margin is small and the payout share is large — the structural feature of an exchange that puts it ahead of a fixed-odds sportsbook on price for the same event. Bookmakers earn revenue from less favourable odds — the gap is the margin — and exchanges earn it from commission, which is paid on winnings rather than built into the price.
Are betting exchanges better value than a fixed-odds sportsbook?
On the markets where both operate against each other, an exchange is generally better value to the punter because the head-to-head price competition narrows the margin below what a single bookmaker can offer. The exchange charges commission on net winnings instead, so the trade-off is upfront versus ongoing — narrower odds with a commission charge versus wider odds with no commission. What the punter pays depends on the sport, the market, the time of day, and the punter’s record on the platform. A side-by-side price check on the day of the bet is the only comparison that holds.
Betting sites & exchanges – tenniscourttips.com
Content created by the «tenniscourttips.com» team
